 DriveHub
Country guide · Malta · 7 min
Car allowance or mileage allowance in Malta: a flat sum, or 35 cents a kilometre with a log
Car allowance or mileage allowance? In Malta, a flat car allowance is taxed on at least half its value. A reimbursement of up to 35 cents a kilometre, backed by a log of every journey, has no taxable value at all.

The short answer
- What are the two options? Your employer can reimburse business kilometres at a rate per kilometre, or pay a flat car cash allowance for the use of your car.
- Is the per-kilometre route taxed? Not if every condition holds: no more than 35 cents a kilometre, business use only, and a log of the purpose, destination and distance of each journey, kept six years. It is then "deemed to have no value".
- Is a car allowance taxed? Yes, as a fringe benefit. Where three conditions hold, its value is cut by 50 %, and the cut is capped at 1 170 € a calendar year across all your employers.
- What if the 35 c conditions fail? The whole reimbursement becomes a fringe benefit, valued the same way as a car allowance. Not just the excess.
- Directors? The Rule and the authority's guide draw the line differently for directors on the allowance. Both are set out below.
Every payment for your car starts as a benefit
Malta's Fringe Benefits Rules, S.L. 123.55, don't separate the two options at first. Rule 17(2)(a) defines a vehicle allowance as "any payment to that individual relating to the use of his vehicle whether by way of reimbursement of costs or otherwise". Rule 18(1) values it at "the total amount so paid".
So a monthly allowance and a per-kilometre reimbursement both start at their full amount. What differs is the way out of that value. The per-kilometre route can take it to nothing. The allowance route takes off at most half, up to a cap, unless you also claim actual costs (below).
Route 1: up to 35 cents a kilometre, with a log
Rule 18(5) deems the payment to have no value where it is a reimbursement of costs "made by reference to the distance actually covered at a rate not exceeding 35 cents per kilometre", and "the employer has logged the details to which any such reimbursement refers, including the purpose, destination and distance of each journey". The figure has stood since 1 January 2008, when Legal Notice 409 of 2007 replaced 15 cents with 35.
The Malta Tax and Customs Administration's Fringe Benefits Tax Guide (p. 14) lists the conditions this way:
- "the rate of payment for each kilometre travelled does not exceed 35 cents per kilometre,"
- "payments only cover the business use element,"
- "all reimbursable travel is recorded in a logbook readily available at any time for verification by the CfR, and"
- "the log book is retained by the employer for at least 6 years."
Rule 48(3) makes the six years hard law: records "shall be kept for a period of not less than 6 years." Rule 47(1) gives the guide the same effect as the Rules, as far as it does not conflict with them.
Two things are easy to get wrong. First, 35 cents is a ceiling, not a rate. Nobody is obliged to pay it, and an employer can pay less. Second, the cash-allowance conditions below (a contract clause, not a director, no other employer car) are not on this list. Some secondary pages attach them to the 35 c; the guide does not.
What goes in each column of the log is in Malta's mileage log template.
Route 2: a car cash allowance
A flat sum for the use of your own car is taxable as a fringe benefit. Rule 18(2) reduces its value by 50 %, but only where all three of these hold:
- "(a) the allowance is paid to an employee in terms of the provisions of a collective agreement or of his contract of service with respect to the use of his vehicle for the purpose of the employer's business; and"
- "(b) the beneficiary is not a person in a controlling position; and"
- "(c) the employee is not entitled to the private use of another vehicle owned or held under a title of lease by the employer"
The reduction is capped: "the maximum total reduction that may be so allowed in any calendar year with respect to any one beneficiary is €1,170". Under rule 18(3), that cap covers the total of your allowances from more than one employer, not each one separately.
The guide (p. 13) adds a fourth condition, "the employee uses his own car", and ends: "When any of the above conditions is not met the full cash allowance is taxable."
Fuel goes into the same pot. If you're on a car cash allowance and your employer also reimburses fuel, the guide says the fuel "is added to that allowance and the 50% or €1,170 maximum deduction applies on the total amount".
Directors: the Rule and the guide disagree
Rule 18(2)(b) excludes only a person in a controlling position. Under rule 2(2), a director is in that position if they hold 25 % or more of the shares or voting rights. More than 50 % together with their family also counts. A director also counts if they are "not registered with the competent authority set up under the Employment and Training Services Act as a whole time employee" with that company.
The guide's condition is wider: "the employee is not a director or a partner or a person in a controlling position of a company or a partnership". It excludes every director and partner.
Rule 47(1) gives the guide effect only "to the extent that they are not in conflict with any rules prescribed". A director registered as a whole-time employee, holding under 25 %, meets the Rule's condition but not the guide's. This page records the conflict; it does not decide it. If that's you, take it to your accountant.
Paying yourself mileage from your own company is its own question, covered in director mileage in Malta.
A worked example
You drive 8 000 business kilometres in a year in your own car. You're an employee, not a director, with no shares in your employer and no company car, and the allowance is in your contract. So the three conditions of rule 18(2), and the guide's four, hold.
| Paid in the year | Value as a fringe benefit | |
|---|---|---|
| 35 c a km, every journey logged | 8 000 × 0,35 € = 2 800 € | 0 € |
| Allowance of 150 € a month | 12 × 150 € = 1 800 € | 1 800 € − 900 € (50 %) = 900 € |
| Allowance of 200 € a month | 12 × 200 € = 2 400 € | 2 400 € − 1 170 € (50 % is 1 200 €, capped) = 1 230 € |
| 35 c a km, one condition failed | 2 800 € | 2 800 € − 1 170 € (50 % is 1 400 €, capped) = 1 630 € |
Above 2 340 € a year in allowances, half is more than 1 170 €, so the cap bites. Every euro above that figure is taxed in full.
Two employers. Two allowances of 2 400 € make 4 800 €. The cap is 1 170 € for both together, not each, so the value is 4 800 € − 1 170 € = 3 630 €.
The table shows the value that is taxed, not the tax itself. The tax depends on your own rate.
If the 35 c fails, it is priced like an allowance
The guide (p. 14) closes the per-kilometre conditions with: "If any one of these conditions is not met, the full reimbursement value will be considered as a fringe benefit and will be subject to the same valuation criteria as a car cash allowance."
So a failed reimbursement starts at the whole amount (rule 18(1)). The 50 % reduction, capped at 1 170 €, comes off it only where the rule 18(2) conditions also hold. That means the payment is made under your contract or a collective agreement. You're also not in a controlling position (in the guide: not a director or partner), and you have no employer car. Otherwise the whole reimbursement is taxed.
The fourth row of the table is that case. This assumes the year's 2 800 € is paid as one reimbursement. One journey missing from the log, and 2 800 € that would have been worth nothing is valued at 1 630 €. Pay 36 cents instead of 35 and it is 2 880 €, valued at 1 710 €. Why one gap counts for the whole reimbursement, not just the missing journey, is in Malta's 35 cents is all or nothing.
On an allowance, you can claim actual costs, with documents
Under rule 18(4), an employee on a vehicle allowance may claim, in their own return, the business share of the car's expenses and wear and tear: "to the extent that such expenses and wear and tear relate to the use of the vehicle for the purpose of his employer's business and are allowable in terms of article 14".
The claim is capped at the amount by which those costs exceed the 50 % reduction already given. It is allowable only if all of these hold:
- the three rule 18(2) conditions are satisfied;
- "the employee is in possession of documents proving the said expenses and the purpose for which they were incurred";
- the full value of the benefit is declared;
- "the claim for the deductions is supported by a computation".
The Rule doesn't name a logbook here. It asks for documents proving the purpose of the costs, and the business share has to be computed. A log of business journeys is one way to show both.
Before you agree to either
- A van or a motorcycle? Neither is a "vehicle" under rule 8, so the 35 c safe harbour does not apply to it. See what is not a vehicle.
- A company car instead? That is valued on the car's value, not your kilometres. See Malta company car and point to point.
- Self-employed? Malta has no per-kilometre figure for you at all; you're on actual costs. See Malta's 35 cents is all or nothing.
How DriveHub makes this easier
On the 35 c route, the money depends on the log being complete. What goes missing is rarely the distance. It is the short journey nobody wrote down, and the purpose of a visit months ago.
With location access set to Always, DriveHub records every drive in the background — and if it ever misses one, it tells you. It keeps the date, both ends and the distance. DriveHub files most trips as Business or Personal by your places, past routes and working hours, and asks you about the rest. You add the purpose in your own words.
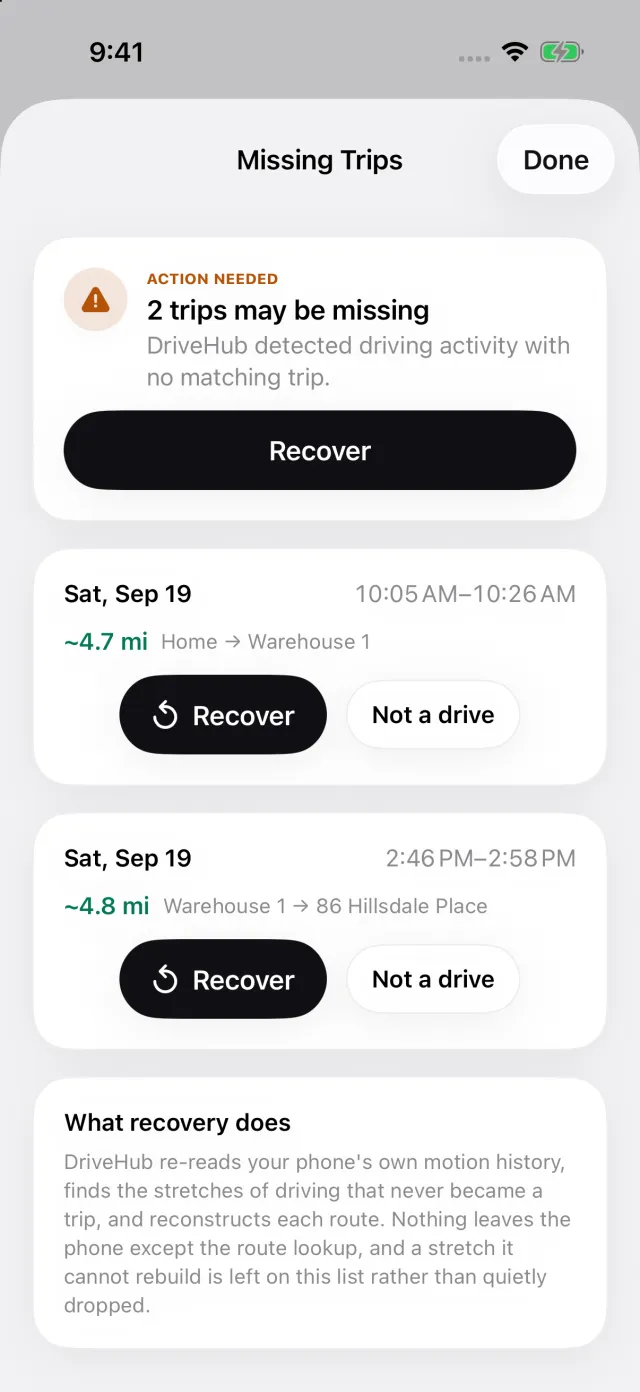
If your iPhone logged driving with no matching trip, a Missed drives story appears on the Trips tab. It opens the list of missing trips, where Recover rebuilds the route, before the log goes to your employer rather than after.
For Malta, the report prints all three prescribed items on every row: the purpose, the destination and the distance. Tracking and the missing-drive check are free; the report is part of DriveHub Pro.
Where DriveHub stops: it doesn't value an allowance, apply the 1 170 € cap or decide whether you're in a controlling position. It sends nothing to your employer or to the tax authority. A drive it didn't record and can't recover, because the phone was off, flat or in Airplane Mode, stays out of the report until you add it by hand.
DriveHub is on the App Store for iPhone. The Maltese rules it follows are on the Malta page, and setting up automatic tracking takes a few minutes, once.
This page states what the Rules themselves say, and names the rule so you can check. It is not tax advice. It can't account for your circumstances. Where money is involved, ask your accountant — and bring the log.
Do it in DriveHub
Employment dates, different rates and trips for more than one job.
The full rule for Malta, with the instruments it comes from: mileage log requirements in Malta.